

AI Hype Cools, Defensive Assets Become New Favorites
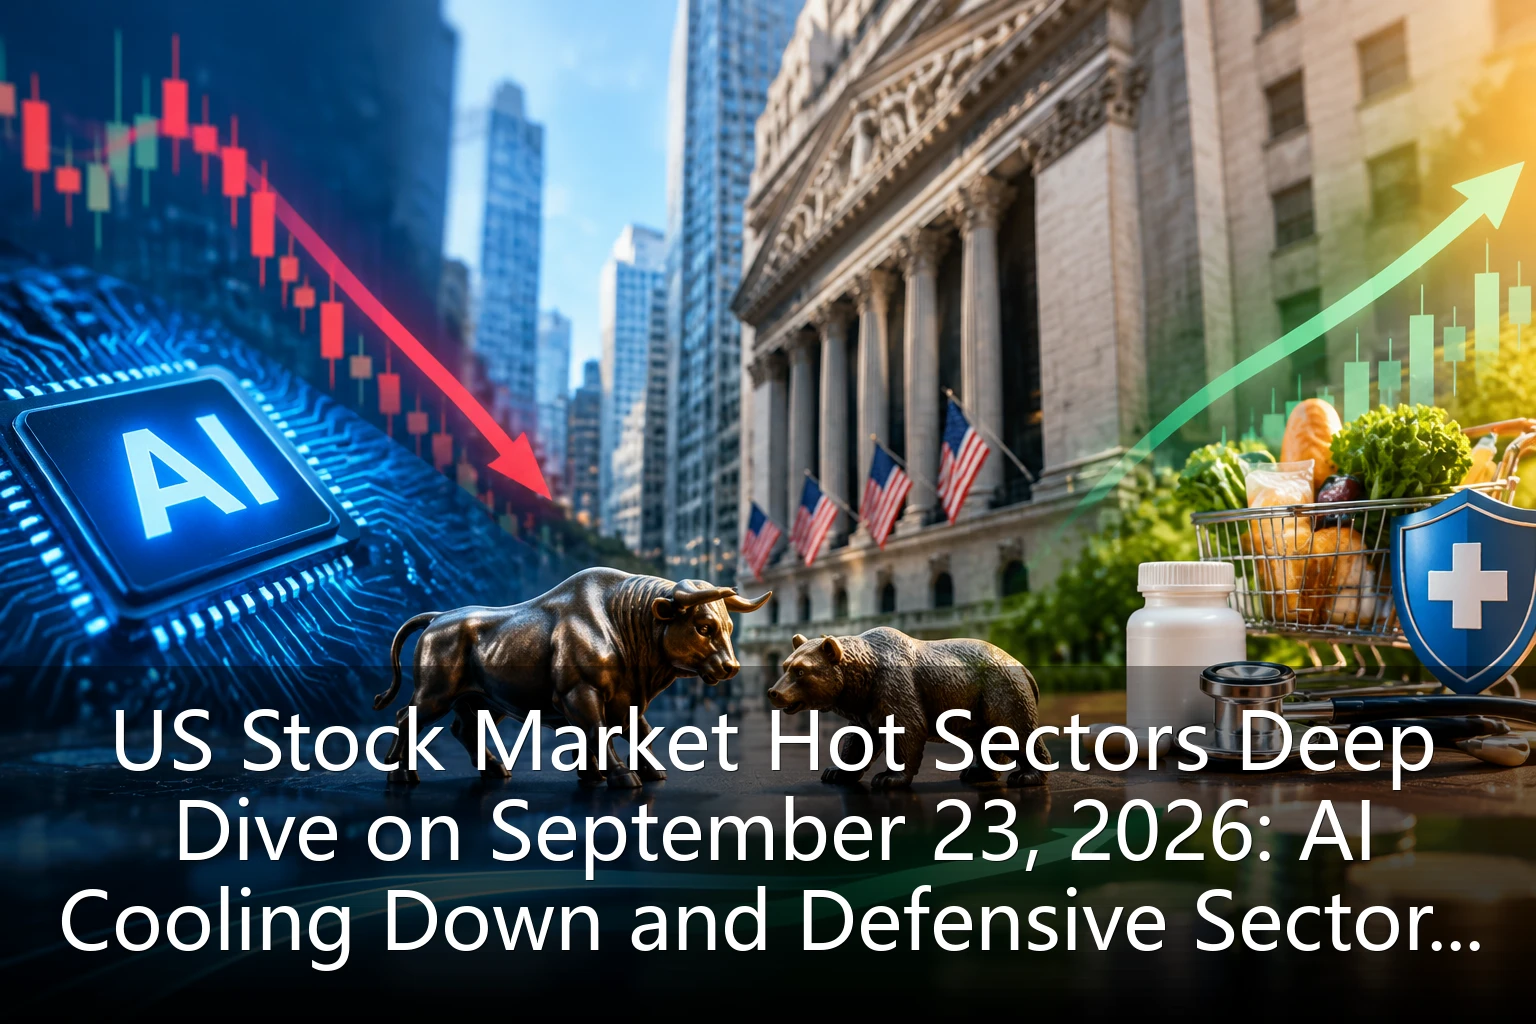
On September 23, 2026, the US stock market showed clear sector rotation characteristics, with major indices fluctuating and closing higher, but internal structure has undergone profound changes. As Q3 nears its end, investors are reassessing market risk appetite, once-hot AI-related sectors are gradually cooling, while defensive sectors like utilities, healthcare, and consumer staples are gaining capital favor. This shift not only reflects market reassessment of economic outlook but also indicates potential direction for Q4 market.
Overall Market Performance: Index Divergence, Style Rotation
As of September 23 close, S&P 500 rose 0.3% to 4,580; Dow Jones Industrial Average edged up 0.1% to 34,350; while tech-heavy Nasdaq fell 0.2% to 14,120. The divergence in major indices shows significant changes in market internal structure. Notably, this marks the third consecutive day Nasdaq underperformed the broader market, reflecting adjustment pressure on tech sector.
In terms of volume, NYSE volume decreased 5% from previous session, Nasdaq volume dropped 8%, showing reduced market participation. However, capital flows between sectors remain unusually active, particularly the shift from tech to defensive sectors.
AI Sector Cooling: From Frenzy to Rationality
After nearly two years of strong performance, the AI sector has recently cooled significantly. Tech stocks represented by semiconductors, cloud computing, and AI applications generally declined, with Philadelphia Semiconductor Index down 1.2% and software services sector down 0.8%. This shift stems from three main factors:
- Valuation Pressure: After continuous gains, AI-related stock valuations have reached historical highs, with some companies' P/E ratios exceeding 50 times, far above industry average.
- Earnings Expectation Revisions: Several AI leaders recently lowered quarterly growth forecasts, sparking concerns about slowing AI commercialization.
- Intensified Competition: As more companies enter AI field, technical barriers gradually decrease, increased competition pressures profit margins.
Specifically, NVIDIA (NVDA) fell 2.3%, AMD (AMD) dropped 1.8%, and Microsoft (MSFT) declined 0.5%. These core AI companies' weak performance dragged down the entire tech sector. Analysts note that AI sector adjustment is not a trend reversal but a normal process from concept hype to value return, with long-term growth logic still intact.
Defensive Sectors' Rise: Capital Safe Havens
In stark contrast to AI sector, defensive sectors like utilities, healthcare, and consumer staples showed strong performance. Utilities Index rose 1.2%, Healthcare Index gained 0.9%, and Consumer Staples Index increased 0.7%. These sectors gained capital favor based on the following logic:
- Increased Economic Uncertainty: As multiple economic data show growth slowing, investors are shifting to defensive assets with stable cash flows.
- Enhanced Dividend Attraction: In high-interest rate environment, high-dividend stocks' relative investment value stands out, with utilities sector averaging 3.5% dividend yield.
- Policy Support: Healthcare benefits from aging population and healthcare reform policies, while consumer staples benefit from consumption resilience.
On individual stock level, NextEra Energy (NEE) rose 2.1%, Johnson & Johnson (JNJ) gained 1.5%, and Procter & Gamble (PG) increased 1.2%. These defensive leaders not only provide stable dividend income but show strong resilience, becoming investors' preferred safe havens.
Capital Flow Changes: Reallocation Signals
According to capital flow data, since September, tech sector has seen three consecutive weeks of net outflows, totaling $28 billion; while utilities, healthcare, and consumer staples sectors gained $12 billion, $10 billion, and $8 billion in net inflows respectively. This reallocation reflects changes in investor risk appetite.
In ETF flows, tech ETFs like XLK and QQQ experienced net outflows, while defensive ETFs such as XLU, XLV, and XLP gained net inflows. Institutional investors are adjusting portfolios, increasing defensive asset allocation and reducing tech positions.
Analysts point out that capital flow changes often precede market style shifts. The current rotation from growth to value stocks and from tech to defensive sectors may signal a new market phase where investors focus more on fundamentals and cash flows rather than pure growth stories.
Economic Data and Policy Environment Impact
Recent economic data have significantly influenced market sector rotation. September manufacturing PMI data shows manufacturing activity continues to slow, with ISM Manufacturing Index dropping to 49.2, below the expansion line for the second consecutive month. This data intensified market concerns about economic slowdown, prompting investors to shift to defensive sectors.
Meanwhile, Fed policy stance also affected market direction. Despite inflation easing, Fed officials recently indicated that rate cuts may be delayed until 2027, with high-interest rate environment persisting longer. This policy stance pressures rate-sensitive tech stocks while benefiting defensive assets with stable cash flows.
Q4 Market Outlook: New Balance Between Defense and Growth
Looking ahead to Q4, the market may enter a new phase balancing defense and growth. On one hand, economic slowdown and increased uncertainty will continue to support defensive sectors; on the other hand, the adjusted AI sector may present opportunities, especially in segments with better-than-expected performance.
Specifically, Q4 market may show the following characteristics:
- Accelerated Sector Rotation: Market will focus more on individual stock fundamentals, sector rotation frequency may increase, requiring more flexible allocation adjustments.
- Defensive Sectors Continue to Benefit: Against economic slowdown backdrop, defensive assets with stable cash flows and dividends will remain favored.
- AI Sector Structural Opportunities: After adjustment, AI companies with real technological advantages and commercialization capabilities will regain attention.
- Cyclical Sector Bottom Rebound: With soft landing expectations strengthening, some cyclical sectors may see valuation recovery opportunities.
Investment Strategy Recommendations: Seizing Style Rotation Opportunities
Facing current market sector rotation characteristics, investors may adopt the following strategies:
- Balanced Allocation: Appropriately increase defensive assets in portfolio while maintaining moderate exposure to tech sector to capture AI sector's structural opportunities.
- Focus on Fundamentals: Pay more attention to companies' cash flows, profitability, and valuation levels rather than pure growth stories and market sentiment.
- Diversified Investment: Diversify across industries and asset classes to reduce impact of single sector volatility on overall portfolio.
- Dynamic Adjustment: Adjust portfolio timely based on economic data changes and policy directions to seize market style rotation opportunities.
Overall, September 23, 2026 market performance reveals new trends in US sector rotation, with the shift from AI hype to defensive assets reflecting market reassessment of economic outlook and risk appetite. Investors should closely monitor these changes and adjust strategies flexibly to seize new opportunities in Q4 market.